541 kr
Skickas inom 10-15 vardagar
541 kr
Skickas inom 10-15 vardagar
2 515 kr
Skickas inom 10-15 vardagar
655 kr
Läs direkt efter köp
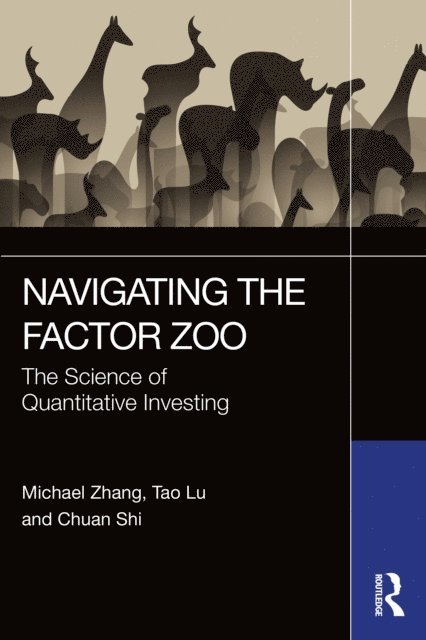
Bridging the gap between theoretical asset pricing and industry practices in factors and factor investing, Zhang et al. provides a comprehensive treatment of factors, along with industry insights on practical factor development.
Chapters cover a wide array of topics, including the foundations of quantamentals, the intricacies of market beta, the significance of statistical moments, the principles of technical analysis, and the impact of market microstructure and liquidity on trading. Furthermore, it delves into the complexities of tail risk and behavioral finance, revealing how psychological factors affect market dynamics. The discussion extends to the sophisticated use of option trading data for predictive insights and the critical differentiation between outcome uncertainty and distribution uncertainty in financial decision-making. A standout feature of the book is its examination of machine learning''s role in factor investing, detailing how it transforms data preprocessing, factor discovery, and model construction. Overall, this book provides a holistic view of contemporary financial markets, highlighting the challenges and opportunities in harnessing alternative data and machine learning to develop robust investment strategies.
This book would appeal to investment management professionals and trainees. It will also be of use to graduate and upper undergraduate students in quantitative finance, factor investing, asset management and/or trading.
646 kr
Läs direkt efter köp
Bridging the gap between theoretical asset pricing and industry practices in factors and factor investing, Zhang et al. provides a comprehensive treatment of factors, along with industry insights on practical factor development.
Chapters cover a wide array of topics, including the foundations of quantamentals, the intricacies of market beta, the significance of statistical moments, the principles of technical analysis, and the impact of market microstructure and liquidity on trading. Furthermore, it delves into the complexities of tail risk and behavioral finance, revealing how psychological factors affect market dynamics. The discussion extends to the sophisticated use of option trading data for predictive insights and the critical differentiation between outcome uncertainty and distribution uncertainty in financial decision-making. A standout feature of the book is its examination of machine learning''s role in factor investing, detailing how it transforms data preprocessing, factor discovery, and model construction. Overall, this book provides a holistic view of contemporary financial markets, highlighting the challenges and opportunities in harnessing alternative data and machine learning to develop robust investment strategies.
This book would appeal to investment management professionals and trainees. It will also be of use to graduate and upper undergraduate students in quantitative finance, factor investing, asset management and/or trading.
660 kr
Skickas inom 10-15 vardagar
868 kr
Läs direkt efter köp
660 kr
Skickas inom 10-15 vardagar
877 kr
Läs direkt efter köp
660 kr
Skickas inom 10-15 vardagar
1 557 kr
Skickas inom 10-15 vardagar
1 948 kr
Läs direkt efter köp
1 575 kr
Skickas inom 10-15 vardagar
1 792 kr
Skickas inom 10-15 vardagar
2 341 kr
Läs direkt efter köp
1 792 kr
Skickas inom 10-15 vardagar